Franchise opportunities for veterans draw on three federal supports: a $0 upfront fee on SBA Express loans through September 30, 2027, free SBA training, and VR&E self-employment aid; fee discounts come only from each franchisor’s Item 5.
Key takeaways
- SBA Express loans to a business owned and controlled by a veteran or a veteran’s spouse carry a $0 upfront guaranty fee for loans approved October 1, 2026 to September 30, 2027 (SBA Information Notice 5000-881797).
- The waiver ends at the Express ceiling of $500,000 written into 15 U.S.C. 636(a)(31)(D); a bigger standard 7(a) loan pays 3% to 3.75% of the guaranteed portion unless a rural or manufacturing exception applies.
- VA’s GI Bill page offers entrepreneurship training through the SBA and says nothing about buying a business; H.R. 10016, which would fund franchise grants from GI Bill entitlement, was introduced on August 3, 2026 and is not law.
- Veteran Readiness and Employment can pay for tools, supplies and license fees in an approved self-employment plan, but 38 CFR 21.214(f) bars payment for land, buildings, leases and vehicles.
- Of 259 FDDs issued 2025 to 2026, 117 (45.2%) cut the initial franchise fee for veterans and 3 of 130 veteran incentives touched royalties, per our coding of veteran franchise discounts.
Which federal programs can a veteran put toward a franchise?
Eight federal programs touch a veteran’s franchise purchase, and only one lowers a cost you would otherwise pay: the SBA Express upfront fee waiver. Four others train you, VR&E funds tools and supplies for veterans with a service-connected rating, MREIDL covers a reservist call-up and VetCert matters for federal contracts. VetFran is run by the International Franchise Association, not an agency, and appears last for comparison.
Programs that put money or equipment into the business
| Program | Who qualifies | What it pays or provides | What it does not cover | Status, November 2026 | Source |
|---|---|---|---|---|---|
| SBA Express veteran fee waiver | A business owned and controlled by a veteran, a TAP-eligible service member, a Reserve member, or a spouse of one of them | $0 upfront guaranty fee on Express loans of up to $500,000 | Interest; any loan above $500,000; SBA guaranty above 50% | In force for loans approved Oct 1, 2026 to Sep 30, 2027 | SBA Notice 5000-881797; 15 U.S.C. 636(a)(31) |
| VR&E self-employment track | Service-connected rating of 10% or more (20% memorandum rating on active duty) plus an employment barrier | Business plan help and training; license fees, tools and supplies; stock and equipment for the most severely disabled | Land, buildings, leases, rentals, vehicles | Plans of $25,000 or more need VR&E Service Executive Director approval | 38 CFR 21.257; 21.258 |
| Military Reservist EIDL | A small business whose essential employee is called to active duty | Up to $2 million for ordinary and necessary operating expenses | Anything beyond the actual economic injury SBA calculates | Available | SBA disaster assistance |
| H.R. 10016 (proposed) | GI Bill-entitled veterans with 36 months of active duty, or 24 if discharged for a service-connected disability | Grants sized to remaining GI Bill entitlement for up to 250 veterans, franchises included | Nothing yet: it is a bill | Introduced Aug 3, 2026; referred to House Committee on Small Business | Bill text |
Programs that train, certify or connect you
| Program | Who qualifies | What it pays or provides | What it does not cover | Status, November 2026 | Source |
|---|---|---|---|---|---|
| Boots to Business and B2B Reboot | Service members, Guard and Reserve, military spouses; Reboot adds veterans of all eras | Two-day in-person course, free at participating installations; online Revenue Readiness follow-on with Mississippi State University | Any funding or brand selection | Running (page read Nov 3, 2026) | SBA Boots to Business |
| Veterans Business Outreach Centers | Service members, veterans, Guard and Reserve, military spouses and family | Counseling and training to start or grow a business, through 31 organizations | Loans or grants | Running | SBA resource partners |
| SDVETP and WVETP training grants | Veterans injured in the line of duty (SDVETP); women veterans and service members (WVETP) | Courses such as the Entrepreneurship Bootcamp for Veterans at St. Joseph’s University and V-WISE | Business funding | Running | SBA training programs |
| GI Bill entrepreneurship training | Post-9/11 GI Bill, MGIB-AD or MGIB-SR; not dependents under DEA | Entrepreneurship training through the SBA | VA’s page names no franchise fee, equipment or purchase | VA page updated Jun 26, 2025 | VA |
| VetCert | Firms at least 51% directly and unconditionally owned, and controlled, by veterans | Access to veteran set-asides in federal contracting | Any discount, grant or loan | Running | 13 CFR 128.202 |
| VetFran (industry, not federal) | Veterans and military-connected families | Free education; member brands pledge an incentive; Star tiers set 10%, 15% and 20% minimum fee discounts | Matching or ranking brands | Star System pages updated 2026 | IFA VetFran |
What none of the eight programs pays for
No line in that register waives a royalty, and none promises to pay an initial franchise fee by name. VR&E’s rule lists “License or other fees required for self-employment” in 38 CFR 21.257(d)(3), but it does not mention franchise fees, so whether a VA counselor treats one as a license fee is a question to put in writing during plan development. For the loan side of the purchase, our franchise financing guide compares SBA, ROBS and franchisor loans.
Is the SBA veteran loan fee waiver in force for fiscal 2027?
Yes. SBA Information Notice 5000-881797, published September 3, 2026, sets the upfront fee at $0 for every SBA Express loan made to a business owned and controlled by a veteran or a veteran’s spouse, for loans approved October 1, 2026 through September 30, 2027. The waiver applies to Express loans only, and the statute caps those at $500,000 with an SBA guaranty of no more than 50%.
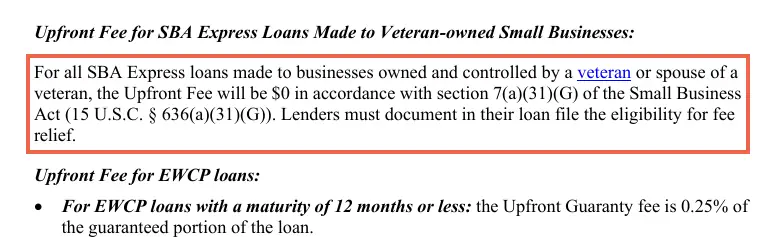
The statute behind the notice, 15 U.S.C. 636(a)(31)(G), has barred the fee on Express loans to veterans since October 1, 2015, and its definition reaches further than most franchisor discounts do. It covers a veteran, anyone eligible for the Transition Assistance Program under 10 U.S.C. 1144, a member of a reserve component, the spouse of any of them, and a surviving spouse when the service member died on active duty or from a service-connected disability.
The notice adds one paperwork rule: “Lenders must document in their loan file the eligibility for fee relief.” It does not set an ownership percentage, so ask the lender which ownership and control test it applies before you split equity with a non-veteran partner. It also states that “Lenders are not permitted to split loans for the purpose of avoiding fees”, and loans approved within 90 days of each other are combined for the fee calculation.
What the waiver is worth at five loan sizes
The figures below apply the FY2027 schedule to an Express loan for a borrower without the exemption: 2% of the guaranteed portion for loans of $150,000 or less and 3% for $150,001 to $700,000, at the 50% guaranty cap and a term over 12 months. The veteran-owned borrower’s fee in every row is $0.
| Express loan | Guaranteed portion at 50% | FY2027 rate on that portion | Fee without the waiver | Fee for a veteran-owned borrower |
|---|---|---|---|---|
| $100,000 | $50,000 | 2% | $1,000 | $0 |
| $150,000 | $75,000 | 2% | $1,500 | $0 |
| $250,000 | $125,000 | 3% | $3,750 | $0 |
| $350,000 | $175,000 | 3% | $5,250 | $0 |
| $500,000 | $250,000 | 3% | $7,500 | $0 |
A veteran-owned borrower pays $0 upfront on every SBA Express loan approved October 1, 2026 to September 30, 2027; a non-exempt borrower pays $1,000 to $7,500 at these sizes. SBA Notice 5000-881797, accessed November 3, 2026.
Above $500,000 the loan has to move to standard 7(a), where the same notice charges 3% of the guaranteed portion up to $700,000, then 3.5% up to $1,000,000 and 3.75% beyond, with a 0% fee for rural and manufacturing loans of $700,000 or less. Our SBA franchise loan data shows how loan sizes for franchises are distributed, and the list of SBA lenders active in franchise lending shows who writes them.
Can GI Bill benefits pay for a franchise?
Not under VA’s current guidance. VA entrepreneurship training page, last updated June 26, 2025, says VA offers entrepreneurship training through the Small Business Administration to people eligible under the Post-9/11 GI Bill, MGIB-AD or MGIB-SR, and it excludes dependents using DEA. It names training only and is silent on franchise fees, equipment or buying a business.
The idea of turning GI Bill months into start-up money sits in Congress. The introduced text of H.R. 10016, the Veterans Entrepreneurship Act of 2026, would create an SBA pilot with these terms:
| Term | What the introduced bill text says |
|---|---|
| Scale | Grants to not more than 250 eligible veterans, with geographic diversity |
| Length | 3 years from the date SBA starts the pilot |
| Qualifying businesses | A list SBA sets by rule that “shall include” a small business concern and a “franchise business enterprise” |
| Who is eligible | Veterans, or members separating with an approved packet, with 36 months of active duty (24 if discharged for a service-connected disability) and entitlement under chapter 30 or 33 |
| Grant size | Remaining months of GI Bill entitlement times the chapter 33 or chapter 30 rate, plus a monthly amount tied to the E-5 housing allowance |
| Conditions before money | Required entrepreneurship training and an approved business plan; franchise applicants show compliance with state and federal franchise laws |
| Status | Introduced August 3, 2026 and referred to the House Committee on Small Business |
Until a version of this becomes law, a franchise plan should not count on GI Bill money for fees or build-out. Check the bill number on congress.gov before relying on it; the text we opened is the version introduced on August 3, 2026.
What will Veteran Readiness and Employment fund in a self-employment plan?
VR&E, VA’s Chapter 31 program, can make self-employment your vocational goal when VA finds it suitable after an initial evaluation (38 CFR 21.257(a)). Per VA eligibility rules, veterans need a service-connected rating of at least 10% and a discharge that was not dishonorable; members still serving need a 20% memorandum rating. Anyone discharged on or after January 1, 2013 has no time limit.
| What VR&E may or may not fund | Who it applies to | Rule in 38 CFR |
|---|---|---|
| Vocational training and incidental training in managing a business | Any approved self-employment plan | 21.257(d)(1) and (2) |
| License or other fees required for self-employment | Any approved self-employment plan | 21.257(d)(3) |
| Necessary tools and supplies for the occupation | Any approved self-employment plan | 21.257(d)(4) |
| Minimum stocks of materials, essential equipment (machinery, fixtures, appliances), business license fees | Veterans with the most severe service-connected disabilities who require self-employment | 21.214(e), through 21.257(e) |
| Not allowed: purchase of, or part payment for, land and buildings | Everyone | 21.214(f)(1) |
| Not allowed: full or part payment of leases or rentals | Everyone | 21.214(f)(2) |
| Not allowed: purchase or rental of trucks, cars or other transportation | Everyone | 21.214(f)(3) |
| Approval: plans under $25,000 by the VR&E Officer; $25,000 or more by the Executive Director, VR&E Service | Everyone | 21.258 |
Before approving a plan, VA must run a feasibility analysis with 7 required elements under 21.257(f), including a cost analysis, a market analysis, financing available from non-VA sources and “Evidence of coordination with the Small Business Administration”. A franchise candidate already holds much of that file: Item 7 of the FDD lists the initial investment, and Item 11 describes the franchisor’s training program.
The exclusions bite hardest on storefront and mobile concepts. A franchise whose Item 7 is mostly lease deposits, rent and a branded vehicle leaves VR&E little it may pay for under 21.214(f), while a home-based service concept with a tool and supply list fits the rule more closely. VA self-employment track page (updated November 15, 2024) lists the services: plan development, concept analysis, small-business training and guidance on resources.
Where do Boots to Business and the outreach centers fit?
They are the free education layer. Boots to Business is a two-day, in-person SBA course inside the Defense Department’s Transition Assistance Program, free at participating installations and open to service members, Guard and Reserve members and military spouses. SBA’s Reboot version extends it to veterans of all eras, and 31 organizations run Veterans Business Outreach Centers.
- Boots to Business: the 2-day course on base; graduates get sign-up details for B2B Revenue Readiness, an online course with Mississippi State University.
- Boots to Business Reboot: “Extends B2B to veterans of all eras in their communities” (SBA veteran business guide).
- Veterans Business Outreach Centers: entrepreneurial development for service members, veterans, Guard and Reserve members, spouses and family, through 31 organizations (SBA resource partners).
- SDVETP and WVETP: SBA-funded courses for veterans injured in the line of duty and for women veterans, run by providers including Oklahoma State University, Warrior Rising and V-WISE (SBA veteran training programs).
- Military Reservist EIDL: up to $2 million for operating expenses when an essential employee is called to active duty, limited to the economic injury SBA calculates (SBA disaster assistance).
None of these programs reviews a specific brand. Their output is a business plan and a set of questions, which is what VR&E’s 21.257(f) review and an SBA lender will ask for. A consultant works on the brand side; our explainer on what a franchise consultant does and how the fee is paid sets out that role.
What does VetFran require of brands, and what does it leave to each FDD?
VetFran is the International Franchise Association’s veterans program, not a federal one. IFA describes VetFran as a free educational resource for veterans and military-connected families, says every VetFran brand offers a veteran incentive, and adds that offers vary and that it does not match veterans to brands. Its 2026 Star System sets minimum initial-fee discounts of 10%, 15% and 20%.
| Star tier | Minimum initial-fee discount | Brand requirements | Source |
|---|---|---|---|
| 1-Star | 10% | 3+ years of continuous franchise operations | IFA, 2026 |
| 3-Star | 15% | 4+ years of operations, an Item 19 financial performance representation, 25+ open units | IFA, 2026 |
| 5-Star | 20% | 5+ years, Item 19, 50+ open units, 80%+ continuity over the past 3 years, at least one Certified Franchise Executive on staff | IFA, 2026 |
| All tiers | n/a | IFA member in good standing with a Clean Audit Report | IFA, 2026 |
A star is a floor on the fee discount, not a verdict on the business. IFA states that a designation “is not a guaranty, representation or warranty” of success and that the Star System “is not a ranking”. In the 259 FDDs we coded, 47.0% of veteran fee discounts reach the 15% 3-Star minimum and 34.2% reach the 20% 5-Star minimum, as our VetFran tier comparison shows.
How do veteran clauses read inside Item 5?
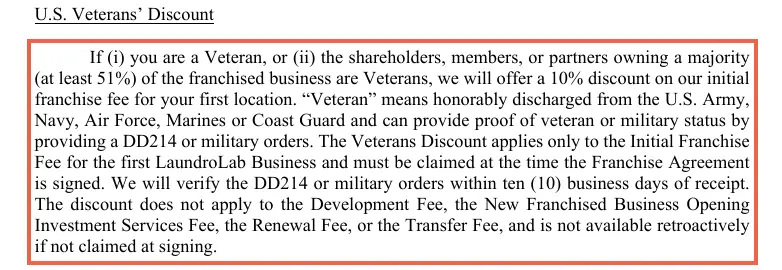
Item 5 of the franchise disclosure document sets out initial fees, so it is where a veteran discount becomes a written term. Four 2026 FDDs filed in Minnesota show four forms: a 10% cut with a 51% ownership test, a full fee waiver paired with a $20,000 deposit, a $5,000 rebate paid at opening, and $20,000 of hand tools with no fee cut.
“If (i) you are a Veteran, or (ii) the shareholders, members, or partners owning a majority (at least 51%) of the franchised business are Veterans, we will offer a 10% discount on our initial franchise fee for your first location.”
That is the LaundroLab Franchise Disclosure Document, issued April 29, 2026 as amended August 24, 2026, Item 5. On its $49,500 initial franchise fee, 10% is $4,950. The same clause leaves the $18,000 New Franchised Business Opening Investment Services Fee untouched, requires a DD214 or military orders, and is “not available retroactively if not claimed at signing.”
“Ziebart® will waive the Initial Franchise Fee to qualified veterans who either have received an honorable discharge from one of the U.S. Military Branches or are currently serving in one of the U.S. Military Branches and eligible to receive an honorable discharge.”
The Ziebart Franchise Disclosure Document, issued April 17, 2026, Item 5 lists a standard initial franchise fee of $45,000. Qualified veterans instead pay a non-refundable Deposit Fee of $20,000 that is credited to the Start-Up Order, so the waiver lowers the fee but not the cash due at signing to zero. Serving members eligible for an honorable discharge are included.
“Matco will provide to each new Distributor whose Principal Owner is an honorably-discharged veteran of the U.S. military who purchases a “standard” or “ETD” Matco Distributorship $20,000 of hand tools (valued at list price) at no charge.”
In the Matco Tools Franchise Disclosure Document, issued April 6, 2026 as amended August 1, 2026, Item 5, the $10,000 initial franchise fee is not reduced; the benefit is inventory valued at list price, and a “225” Distributorship receives $13,500 of hand tools instead. Read side by side, the four offers differ in timing, form and who qualifies:
| FDD (CARDS link) | Issued, item | Standard initial fee | Veteran offer as written | Who qualifies | Limits |
|---|---|---|---|---|---|
| LaundroLab | Apr 29, 2026 (amended Aug 24, 2026), Item 5 | $49,500 | 10% off the initial fee for the first location ($4,950) | Honorably discharged Army, Navy, Air Force, Marines or Coast Guard; veterans own at least 51% | First location; claim at signing; excludes the $18,000 services fee |
| Ziebart | Apr 17, 2026, Item 5 | $45,000 | Initial fee waived; $20,000 non-refundable deposit credited to the Start-Up Order | Honorable discharge, or currently serving and eligible for one | Development Fee for a veteran: $0, $30,000, $15,000 for locations 1 to 3 |
| Great Clips | Mar 30, 2026, Item 5 | $20,000 | $5,000 rebate of the initial fee | Honorably discharged U.S. or Canadian veterans meeting VetFran requirements | Paid when the first salon opens; first salon only |
| Matco Tools | Apr 6, 2026 (amended Aug 1, 2026), Item 5 | $10,000 ($7,000 for a “225”) | $20,000 of hand tools at list price ($13,500 for a “225”) | Principal Owner is an honorably discharged U.S. veteran | Fee unchanged; may be used to acquire additional franchises |
Those four clauses mirror the conditions found across a wider sample. Of 130 FDDs with a veteran incentive in our 259-FDD coding, the most common conditions are shown below; only 3 of the 130 reduced or credited royalties, so nearly every offer is a one-time saving.
76.9% of 130 FDD veteran incentives require an honorable discharge or DD-214 and 40.0% apply to the first unit only; 7.7% extend to spouses. Minnesota CARDS FDDs issued 2025 to 2026, coded October 2026.
| Condition written in the FDD | FDDs (of 130) | Share |
|---|---|---|
| Honorable discharge or DD-214 required | 100 | 76.9% |
| First unit (or one unit) only | 52 | 40.0% |
| Minimum ownership share stated for the veteran | 37 | 28.5% |
| Active-duty or currently serving members eligible | 31 | 23.8% |
| Cannot be combined with other discounts | 30 | 23.1% |
| First responders in the same program | 15 | 11.5% |
| Spouses or family members eligible | 10 | 7.7% |
| Reserve or National Guard named | 6 | 4.6% |
The FDD is a disclosure; the signed contract governs. Compare the Item 5 wording with the discount section of the franchise agreement you will sign, and see how veteran offers sit beside territory and multi-unit pricing in our franchise fee breakdown across 259 filings. The guide to reading all 23 FDD items covers the rest of the document.
Does a franchise count as veteran-owned for VetCert?
It can. SBA’s VetCert rules require veterans to own at least 51% of the business directly and unconditionally (13 CFR 128.202) and to control both long-term decisions and day-to-day operations, with a qualifying veteran in the highest officer position (13 CFR 128.203). Standard franchise controls are usually not the obstacle.
13 CFR 121.103(i) says restraints on “standardized quality, advertising, accounting format and other similar provisions” generally do not make a franchisor an affiliate, provided the franchisee “has the right to profit from its efforts and bears the risk of loss commensurate with ownership.” The same rule says affiliation can still arise through common ownership, common management or “excessive restrictions upon the sale of the franchise interest”, so the transfer section of the agreement is the part to read with VetCert in mind. VetCert matters only if the franchise will sell to federal agencies.
Matching your service status to a program
Start from your service status, then your borrowing need, then the FDD. The table holds the same order as the flowchart below, with the threshold or document each step turns on, current for SBA approvals from October 1, 2026 to September 30, 2027 and VA pages checked November 3, 2026.
| If your situation is | Start with | Threshold or document to check |
|---|---|---|
| On active duty, in the Guard or Reserve, or a military spouse | Boots to Business on an installation | 2-day course; free at participating installations |
| Veteran of any era with no installation access | Boots to Business Reboot or a VBOC | 31 VBOC organizations nationwide |
| Service-connected rating of 10% or more and an employment barrier | VR&E self-employment track | Plan of $25,000 or more needs VR&E Service Executive Director approval; no land, leases or vehicles |
| GI Bill entitlement left (Post-9/11, MGIB-AD, MGIB-SR) | SBA entrepreneurship training through VA | Training only; H.R. 10016 grants are not law |
| Borrowing $500,000 or less; a veteran or spouse owns and controls | SBA Express | $0 upfront fee; SBA guaranty no more than 50% |
| Borrowing more than $500,000 | Standard 7(a) | 3% to 3.75% of the guaranteed portion; 0% if rural or manufacturing at $700,000 or less |
| A military spouse buying alone | SBA Express fee waiver, then Item 5 | Spouses qualify by statute; 7.7% of FDD veteran incentives name spouses |
| Plan to sell to federal agencies | VetCert | 51% direct, unconditional veteran ownership plus control |
| Comparing two brands’ veteran offers | Item 5 of each FDD | First unit only in 40.0% of offers; royalties touched in 3 of 130 |
Program rules and fee notices change each fiscal year; this page is general information, not legal, financial or investment advice. Confirm SBA fee status in the notice in force on your loan’s approval date and VR&E coverage with your counselor in writing.
How we compiled this
In November 2026 we opened 22 primary documents: SBA Information Notice 5000-881797, 15 U.S.C. 636, six eCFR sections (38 CFR 21.214, 21.257 and 21.258; 13 CFR 121.103, 128.202 and 128.203), seven SBA and three VA program pages, the introduced text of H.R. 10016, two IFA VetFran pages and four 2026 FDDs from Minnesota CARDS. Discount shares come from our coding of 259 FDDs issued 2025 to 2026. We excluded brand rankings, earnings data and any program page we could not open at its source.
Frequently asked questions
Can I use my GI Bill to buy a franchise?
Not under current rules. VA’s entrepreneurship training page says GI Bill users under the Post-9/11 GI Bill, MGIB-AD or MGIB-SR can take entrepreneurship training through the SBA; it does not cover fees, equipment or a purchase. H.R. 10016, introduced on August 3, 2026, would let up to 250 veterans turn remaining entitlement into business grants, franchises included, but it is a bill, not law (VA).
Do veterans pay a lower SBA loan fee on a franchise loan?
On SBA Express loans, yes. For loans approved October 1, 2026 to September 30, 2027, the upfront fee is $0 when a veteran or a veteran’s spouse owns and controls the business. Express loans top out at $500,000, so on the largest one the waiver saves $7,500 at a 50% guaranty. Standard 7(a) loans carry no veteran exception (SBA Notice 5000-881797).
Will VA pay for a disabled veteran to start a franchise?
VR&E can approve self-employment as a goal for veterans with a service-connected rating of at least 10% and an employment barrier. It may pay for training, license fees, tools and supplies, and for the most severely disabled, minimum stock and essential equipment. 38 CFR 21.214(f) bars payment for land, buildings, leases or rentals and vehicles, and plans of $25,000 or more need national approval (38 CFR 21.257).
Do military spouses qualify for veteran franchise programs?
For the SBA Express fee waiver, yes: 15 U.S.C. 636(a)(31)(G) includes the spouse of a veteran, of a TAP-eligible member or of a Reserve member, plus some surviving spouses. Boots to Business and VBOCs also serve spouses. Franchisor discounts are narrower: 7.7% of FDDs with a veteran incentive in our 259-FDD coding name spouses or family (15 U.S.C. 636).
Is VetFran a government program?
No. VetFran is run by the International Franchise Association. IFA calls it a free educational resource for veterans and military-connected families, says all VetFran brands offer a veteran incentive, and sets Star tiers with minimum initial-fee discounts of 10%, 15% and 20%. IFA states that a star is not a ranking and that it does not match veterans to brands (IFA).
Can active-duty service members get franchise veteran discounts?
Sometimes. In our coding of 259 FDDs, 23.8% of veteran incentives extend to active-duty or currently serving members, and 76.9% require an honorable discharge or DD-214. Ziebart’s 2026 Item 5, for one, waives its $45,000 fee for members currently serving who are eligible for an honorable discharge. Read the eligibility words in each brand’s Item 5 (Ziebart FDD).
Sources
- SBA Information Notice 5000-881797: 7(a) Fees Effective October 1, 2026 for Fiscal Year 2027, U.S. Small Business Administration. Accessed November 3, 2026.
- 15 U.S.C. 636(a)(31), Express loans and guarantee fee waiver for veterans, Legal Information Institute, Cornell Law School. Accessed November 3, 2026.
- Boots to Business, U.S. Small Business Administration. Accessed November 3, 2026.
- Veteran-owned businesses (business guide), U.S. Small Business Administration. Accessed November 3, 2026.
- Resource partners: Veterans Business Outreach Centers, U.S. Small Business Administration. Accessed November 3, 2026.
- Veteran entrepreneurship training programs, U.S. Small Business Administration. Accessed November 3, 2026.
- Disaster assistance: Military Reservist Economic Injury Disaster Loans, U.S. Small Business Administration. Accessed November 3, 2026.
- Entrepreneurship training (GI Bill), U.S. Department of Veterans Affairs. Accessed November 3, 2026.
- Eligibility for Veteran Readiness and Employment, U.S. Department of Veterans Affairs. Accessed November 3, 2026.
- VR&E Self-Employment track, U.S. Department of Veterans Affairs. Accessed November 3, 2026.
- 38 CFR 21.257, Self-employment, eCFR. Accessed November 3, 2026.
- 38 CFR 21.258, Cost limitations on approval of self-employment plans, eCFR. Accessed November 3, 2026.
- 38 CFR 21.214, Furnishing supplies for special programs, eCFR. Accessed November 3, 2026.
- 13 CFR 128.202, Ownership of a VOSB or SDVOSB, eCFR. Accessed November 3, 2026.
- 13 CFR 128.203, Control of a VOSB or SDVOSB, eCFR. Accessed November 3, 2026.
- 13 CFR 121.103, Affiliation (paragraph (i), franchise and license agreements), eCFR. Accessed November 3, 2026.
- H.R. 10016, Veterans Entrepreneurship Act of 2026 (introduced text), U.S. Government Publishing Office. Accessed November 3, 2026.
- VetFran for Brand Partners (Star System), International Franchise Association. Accessed November 3, 2026.
- Franchising for Veterans (VetFran), International Franchise Association. Accessed November 3, 2026.
- LaundroLab Franchise Disclosure Document, issued April 29, 2026 as amended August 24, 2026, Item 5, Minnesota Department of Commerce, CARDS. Accessed November 3, 2026.
- Ziebart Franchise Disclosure Document, issued April 17, 2026, Item 5, Minnesota Department of Commerce, CARDS. Accessed November 3, 2026.
- Great Clips Franchise Disclosure Document, issued March 30, 2026, Item 5, Minnesota Department of Commerce, CARDS. Accessed November 3, 2026.
- Matco Tools Franchise Disclosure Document, issued April 6, 2026 as amended August 1, 2026, Item 5, Minnesota Department of Commerce, CARDS. Accessed November 3, 2026.